How a Water Damage Insurance Claim Actually Works
Document first, mitigate immediately, open the claim, meet the adjuster with evidence, agree the scope, complete the repairs, then claim back the depreciation before the deadline. Most of what goes wrong happens in the first 48 hours.
Call (719) 618-9013 — 24/7, someone answers.
- IICRC-certified technicians
- Documentation in the format adjusters expect
- Colorado Springs and El Paso County
The process
The nine steps, in order
Before the detail, here is the whole shape of it. Most people only learn step eight exists after they have missed it.
- 1
Stop the water and make it safe
- 2
Document everything before anything moves
- 3
Start mitigation — do not wait for the adjuster
- 4
Open the claim
- 5
Meet the adjuster with your evidence
- 6
Agree the scope, or supplement it
- 7
Receive the first payment — the ACV cheque
- 8
Complete the repairs and claim the recoverable depreciation before the deadline
- 9
Close the claim, and fix the underlying cause
The process
Step 1 — Stop the water and make it safe
Shut off the water at the main if the source is inside the building. Cut power to the affected area at the breaker if the panel is dry and reachable; if it is not, leave it and say so when you call.
Do not enter the water if it came from a sewer line, a septic system or from outdoors. That is Category 3 water — it carries pathogens and needs containment and protective equipment.
The process
Step 2 — Document everything before anything moves
This is the step that decides the claim, and it takes about ninety seconds.
Wide shots of each affected room, then close-ups of damaged materials, then contents in place before they are lifted. Then a slow video walkthrough, narrated, saying the date aloud.
And the one almost everyone loses: photograph the actual failure before it is repaired. The split pipe, the failed supply hose, the cracked fitting. Ask the plumber to keep the removed section. A clean break is evidence of a sudden event; corrosion and scale around it tell a different story — and that distinction decides more water claims than anything else.
Insurance
Step 3 — Start mitigation. Do not wait for the adjuster
This is the most common and most expensive mistake in the whole process.
Most policies place a duty on you to take reasonable steps to prevent further damage after a loss. Waiting three days for an adjuster while water sits does not protect the claim — the additional damage accrued during the wait may be attributed to your delay rather than the original event.
Two clocks are running. Water keeps migrating into more material, and microbial growth begins in roughly 24 to 48 hours on wet porous material. Extraction and drying should start in hours.
Call (719) 618-9013. Someone answers, and mitigation can begin before your claim number exists.
Call (719) 618-9013Insurance
Step 4 — Open the claim
Call your carrier. Have ready: the date and time you discovered it, what you believe failed, what has been affected, what you have already done, and the name of your restoration contractor.
Get and write down: your claim number, the adjuster's name and direct contact, and the expected timeline for inspection.
Two things to ask on this first call:
Which deductible applies
the standard one, or the separate wind and hail deductible? In Colorado the second is usually much larger and frequently a percentage of your dwelling limit.
Is this policy actual cash value or replacement cost?
That single answer determines the entire payment structure downstream.
Insurance
Step 5 — Meet the adjuster with your evidence
Walk the property with them rather than waiting in another room. The scope is built largely from what is visible and what you raise on the day.
Have the folder ready: photographs from before anything moved, the failure-point image, day-one moisture readings, the mitigation scope, your contents inventory and your declarations page.
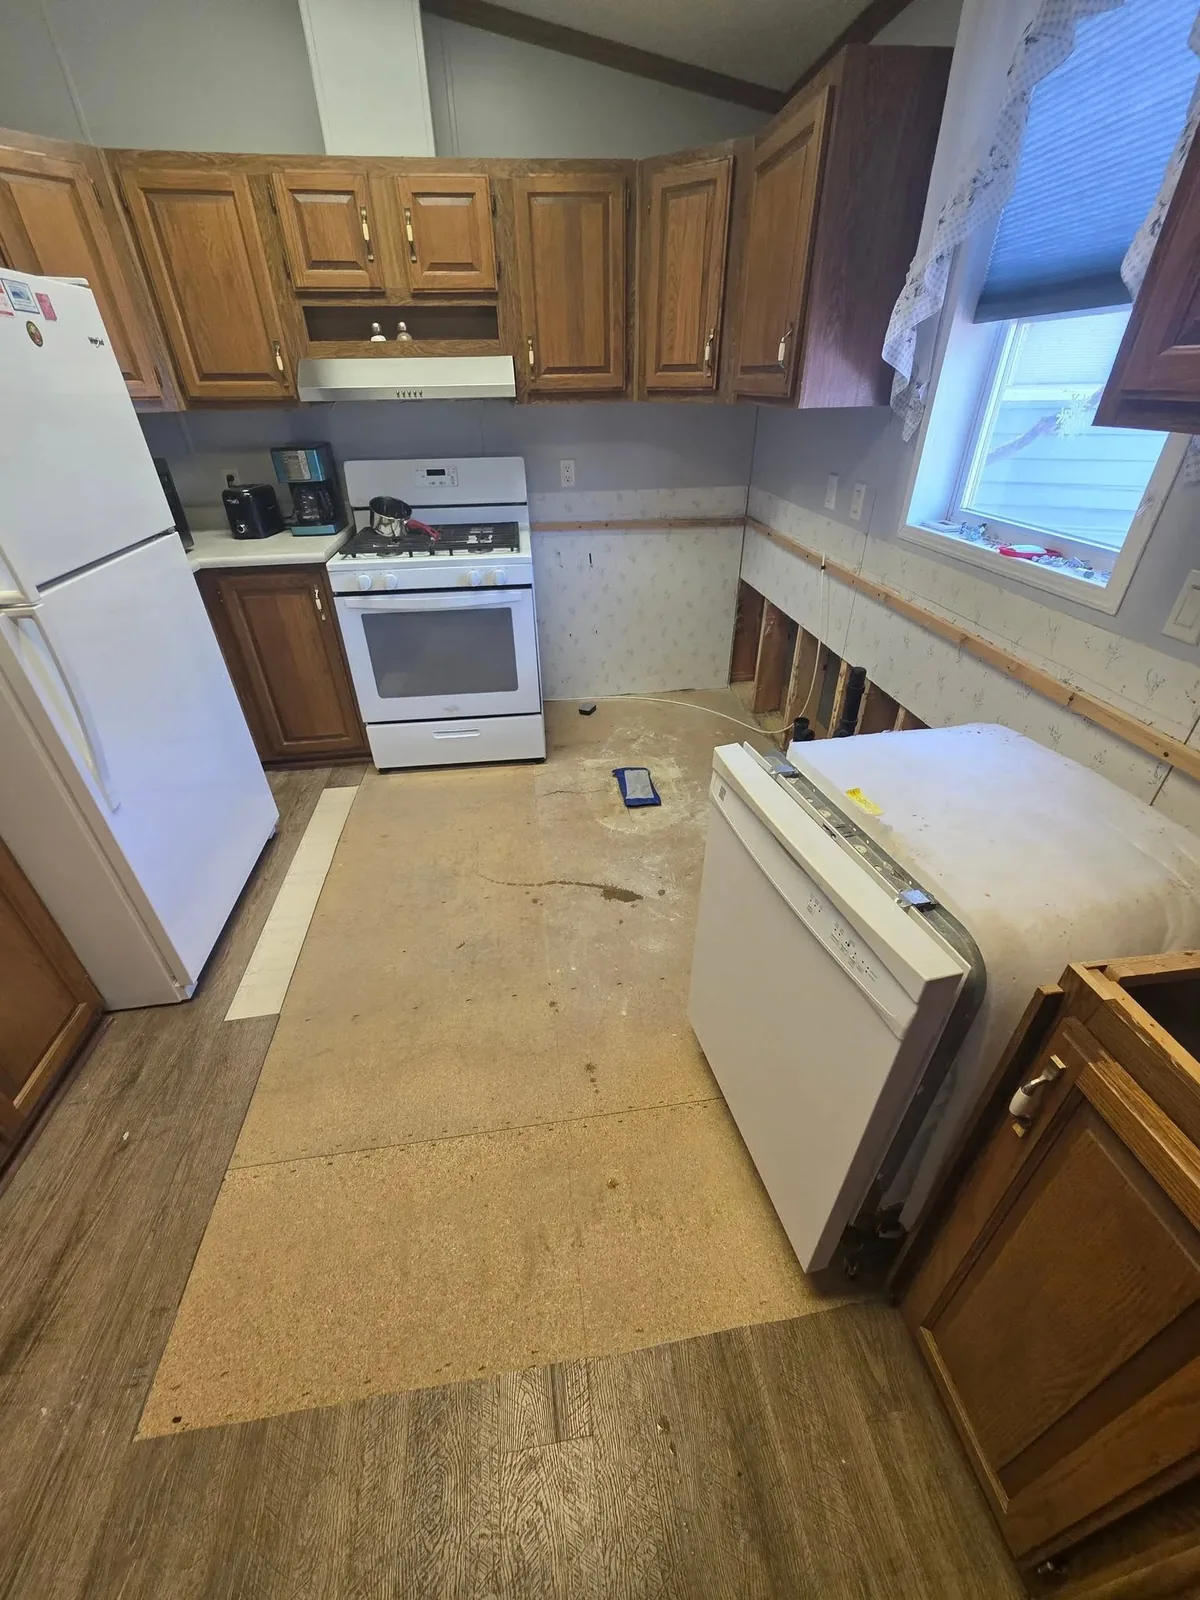
Ask directly: "Are you scoping to the moisture readings, or to what is visible?" In this climate that question matters more than almost anywhere — dry air leaves surfaces feeling dry while the assembly behind them is still wet, so an inspection based on touch will understate the wet area. Hand over the log.
Water on the floor right now?
Tell us where it came from and how long it has been there. We will give you a time, not a window.
Call (719) 618-9013The process
Step 6 — Agree the scope, or supplement it
You will receive an estimate, usually produced in Xactimate as a list of line items. Ask for the full line-item document, not a summary page — a summary is not checkable.
If material is missing, that is a supplement: a request to add scope, supported by documentation. Supplements are routine on water losses, because the full extent is often only visible once material comes out.
If you disagree: request a re-inspection, supply the evidence, have your contractor speak to the adjuster directly, then escalate internally. Most scope disputes resolve in one conversation between two people using the same vocabulary.
The process
Step 7 — Receive the first payment
It will be smaller than the estimate, and that is by design rather than an error.
If your policy settles at replacement cost, the carrier pays actual cash value first — the replacement cost minus depreciation — and takes your deductible off that. The withheld depreciation comes later.
If you have a mortgage, expect your lender to be named on the cheque on anything beyond a modest amount. That means endorsing it to them and funds being released in stages against inspections. Call your servicer early and ask about their process and thresholds, because that timeline often determines when work can start.
Insurance
Step 8 — Complete the repairs and claim the depreciation
This is the step people miss, and it costs them real money.
The withheld depreciation is recoverable — but only against repairs actually completed and documented. You submit the invoices, and the carrier releases the second payment.
There is a deadline. Policies commonly require repairs to be completed and the holdback claimed within a period often falling between 180 days and one year from the date of loss. Miss it and the money is gone.
Three things to establish on day one and write down: how much is being withheld, exactly what documentation releases it, and what the deadline is. If the repair will run past it for a legitimate reason, ask in writing for an extension before the date passes.
Insurance
Step 9 — Close the claim, and fix the cause
Two separate jobs, and the second is the one that protects you.
Repairing the damage restores the building. Fixing the cause is what stops it recurring — and a recurrence is what turns a one-off claim into a pattern, which is what actually affects renewal and underwriting.
Depending on what happened: replace ageing supply lines, fit a backflow valve on the sewer lateral, add a sump with battery backup, correct grading and extend downspouts, clear and drain window wells, insulate pipes in exterior walls and unheated spaces.
Tell your agent what you fixed. Underwriting sees claims automatically. It does not automatically see remediation.
Colorado Springs
What can go wrong, and where
The five failure points, mapped to the step where they happen.
| Step | What goes wrong | What prevents it |
|---|---|---|
| 2 | The failure point is repaired and removed before it is photographed | Ask the plumber to keep the section |
| 3 | Mitigation is delayed while waiting for the adjuster | Start drying; the duty to mitigate is yours |
| 5 | The adjuster scopes to what is visible | Hand over the moisture log and ask the question |
| 6 | Hidden damage is found but not documented before it is removed | Photograph every cavity once it is open |
| 8 | The depreciation deadline passes | Write the date down on day one |
Colorado Springs
How long does the whole thing take?
A rough shape, though it varies with scope and with how busy the market is.
Mitigation and drying
typically three to five days, longer for dense materials or unheated spaces
Adjuster inspection
usually within days, though it stretches significantly after a regional storm event
First payment
commonly a few weeks after the scope is agreed
Reconstruction
depends entirely on scope, materials and contractor availability
Recoverable depreciation
after completion and invoice submission
After a significant hail event, every one of those stretches. Carriers surge independent adjusters into the region, contractors run at capacity, and out-of-area firms arrive. Hail accounts for 26% to 54% of a Colorado homeowner's premium depending on county — roughly 50% along the Front Range — according to the Colorado Division of Insurance's February 2026 analysis of data covering about 80% of the market across 11 counties. That share reflects how often serious storms land here, and how often the whole claims system is under load at once.
Insurance
What is different about a water claim in Colorado Springs?
Four things worth carrying through the whole process.
Losses are found late
Dry air pulls moisture off exposed surfaces while the assembly behind them stays wet — no condensation, no smell. A loss discovered late looks larger and is more likely to attract a gradual-damage argument. Meter rather than touch, and say so to the adjuster.
Cove joint seepage is usually not covered
Water along the edges of a basement floor with no plumbing failure upstream is typically expansive clay pressing groundwater through the floor-to-wall seam. Homeowners policies generally exclude it and flood policies generally do not reach it. Establish the source early.
Your wind and hail deductible may be a percentage
Most major Colorado carriers have moved to 1–5% of the dwelling limit, applied particularly along the I-25 corridor, which includes Colorado Springs. On a hail-characterised loss that can exceed the claim entirely.
Flooding is excluded, and the burn scars matter
Homeowners policies do not cover flood. Below the Waldo Canyon and Black Forest scars, runoff can arrive within about 15 minutes of heavy rain — a genuine exposure that sits outside your policy.
The process
What happens when you call
- 1
We start mitigation
before the claim number exists if necessary.
- 2
We document as we work
Moisture log, photographs, line-item scope. You get a copy whether or not we do the reconstruction.
- 3
We will speak to your adjuster directly
if you want us to.
Call (719) 618-9013 — Colorado Springs and El Paso County, 24/7.
Call (719) 618-9013FAQ
Frequently asked questions
Do I call my insurer or a restoration company first?
Either, but do not let one wait on the other. Mitigation is time-sensitive and most policies require you to prevent further damage. Photograph everything, then make both calls.
How long do I have to file a water damage claim?
Report it as soon as you reasonably can. Policies contain notice requirements and a delay between discovery and reporting is one of the most damaging facts in a water claim. If you have already delayed, file anyway and be accurate about the timeline.
Can I choose my own contractor?
Yes. Your insurer may recommend one from a panel, but you decide who works on your home, and Colorado has protections against being pressured on that point.
Why is my first cheque so much smaller than the estimate?
It is the actual cash value payment — replacement cost minus depreciation — with the deductible taken off. If your policy is replacement cost, you recover the withheld depreciation after repairs are complete.
What if more damage is found after the adjuster has been?
That is a supplement, and it is routine on water losses. Document what was found, when and by whom, and submit it through your adjuster with photographs and readings.
Do I have to use the settlement on the repairs?
If you want the recoverable depreciation, effectively yes — it is released against completed, documented work. If there is a mortgage on the property your lender will also have requirements about how funds are released.
Call (719) 618-9013 — 24/7, Colorado Springs and El Paso County.
Call (719) 618-9013Colorado Homeowners Water Damage Insurance Claims & Xactimate Billing
🛠️ Deployed Equipment & Instrumentation
Xactimate line-item software, moisture log graphing tools, digital timestamped photo inventories, psychrometric daily logs
💰 Colorado Springs Cost & Insurance Billing
100% Direct insurance carrier billing. Homeowner only pays standard policy deductible (typically $1,000 – $2,500).
📋 Certified Operational Standard & Procedures
Comprehensive claim documentation compiled in accordance with Colorado Department of Regulatory Agencies (DORA) standards. Itemized line items matched to current El Paso County labor and material price lists.
🏔️ High-Altitude Atmospheric Drying Physics (6,035 ft Elevation)
Local knowledge of Front Range freeze-thaw exclusions vs sudden burst pipe coverage ensures insurance adjusters receive indisputable thermal documentation of sudden loss.
This resource has been compiled and reviewed under the ANSI/IICRC S500 Standard and Reference Guide for Professional Water Damage Restoration, Colorado Department of Regulatory Agencies (DORA) insurance requirements, and El Paso County regional building codes. For on-site moisture assessments in Colorado Springs, call (719) 618-9013.